Debunking the Biggest Retirement Planning Myths: The Fairy Tales We Tell Ourselves About Growing Old and Getting Rich
Retirement planning is one of the great modern acts of magical thinking.
 By Daniel Buck
Financial Retirement Researcher
Published May 2026 · Last reviewed September 15, 2026 against current IRS, SSA, Medicare, and HHS sources

Key Takeaways
- Start early, but late starters still have powerful levers. Catch-up contributions and delayed Social Security change the math significantly.
- The 4% rule is a historical stress test, not a command. Flexible spending strategies hold up better under real conditions.
- One million dollars is an arbitrary symbol. Cash flow and fixed expenses matter more than any round number.
- A 401(k) alone is not a retirement plan. Diversify tax treatments across Roth, HSA, and taxable accounts.
- Paying off a low-rate mortgage early is often emotional, not optimal, though peace has genuine value.
- Social Security and Medicare are floors, not full solutions. Long-term care remains the largest uncovered risk most people ignore.
Table of Contents
Key Takeaways
- Start early, but late starters still have powerful levers. Catch-up contributions and delayed Social Security change the math significantly.
- The 4% rule is a historical stress test, not a command. Flexible spending strategies hold up better under real conditions.
- One million dollars is an arbitrary symbol. Cash flow and fixed expenses matter more than any round number.
- A 401(k) alone is not a retirement plan. Diversify tax treatments across Roth, HSA, and taxable accounts.
- Paying off a low-rate mortgage early is often emotional, not optimal, though peace has genuine value.
- Social Security and Medicare are floors, not full solutions. Long-term care remains the largest uncovered risk most people ignore.
People will spend six weeks comparing boutique hotels in Lisbon, reading 143 reviews about whether the shower pressure is acceptable.
Then they casually improvise the financial architecture of the last thirty years of their lives like it’s a side quest. It’s astonishing.
We plan vacations with military precision and old age with vibes. Somewhere along the way, retirement became less a financial strategy and more a mythology industry.
Everyone has inherited a phrase, a slogan, a little proverb passed down like family silver.
You need a million dollars. Pay off the house first. Social Security will take care of it.
Just work a little longer. These ideas circulate with the confidence of revealed truth and roughly the same evidentiary standards as medieval medicine.
The trouble is that retirement planning myths are rarely harmless. They are expensive stories, stories with invoices attached. A bad assumption at thirty compounds into a crisis at sixty-five. That’s the perversity of it.
This retirement-planning guide is part of HNI’s Eight Dimensions of Wellness framework and its Financial Wellness coverage.
Finance is one of the few arenas where being slightly wrong for a very long time can be catastrophic. This is not merely about numbers.
It is about psychology, about the stories people tell themselves to avoid confronting time, fragility, and the deeply uncomfortable fact that someday the body will no longer cooperate with ambition.
Retirement planning, stripped of its euphemisms, is really a philosophical confrontation with mortality dressed up as spreadsheets.
And because that truth is unpleasant, retirement planning myths rush in to comfort us. Let’s ruin a few of them, using current guidance from the Internal Revenue Service, the Social Security Administration, Medicare, and other primary sources.
 Good retirement planning is built on honest numbers, not comforting slogans.
Myth #1: Is It Really Too Early to Think About Retirement?
Why does starting late sabotage long-term wealth more than almost any other decision?
This is the financial equivalent of saying you are too healthy to think about health. Youth has a strange relationship with time.
In your twenties, forty years feels less like a duration and more like science fiction. Retirement exists in the same mental drawer as Mars colonies and immortality startups.
The problem, of course, is that markets are indifferent to your sense of narrative timing.
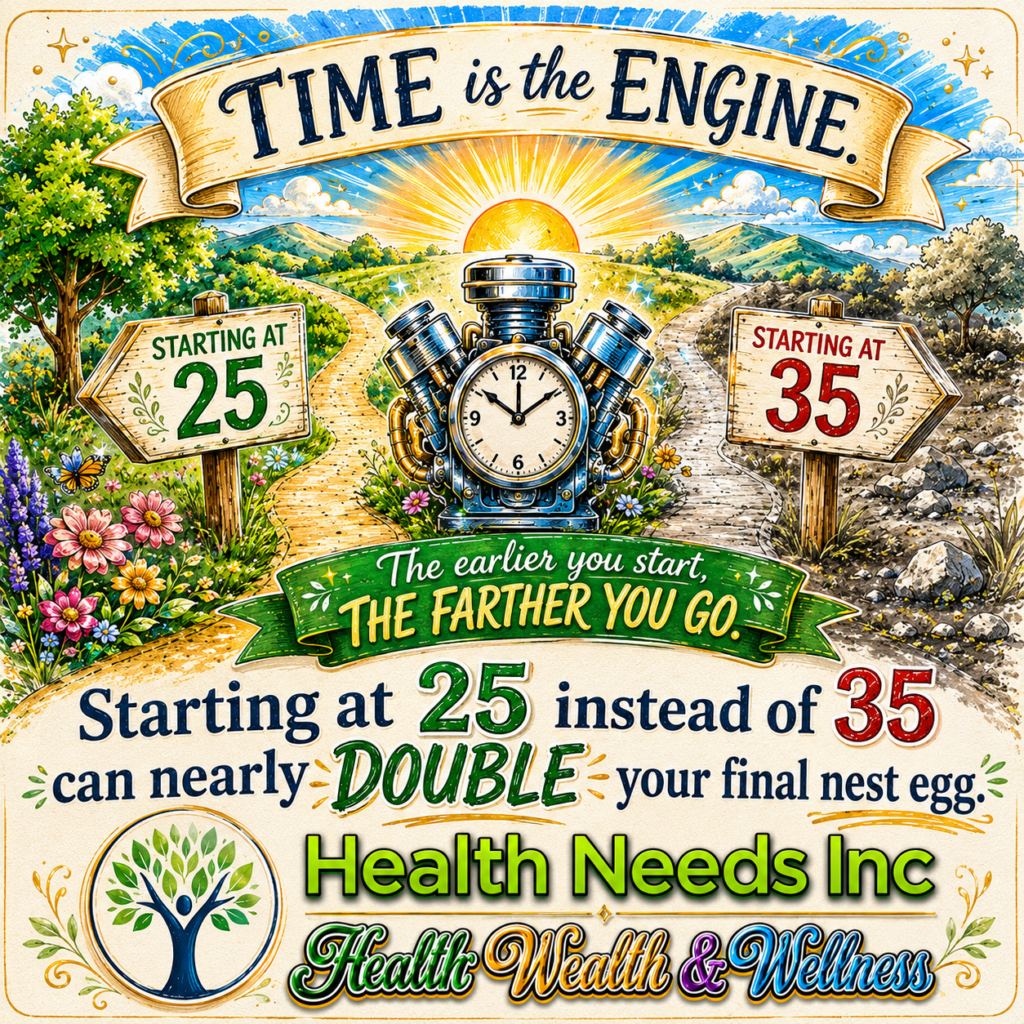
Time is not merely helpful here. Time is the whole machine. According to the SEC's compound interest calculator, delaying a decade cuts final wealth roughly in half, even with identical contributions.
Someone who starts saving early often contributes dramatically less money and still ends up wealthier than the person who starts later with far more discipline.
This is one of finance's rudest truths.
The market rewards the person who arrives first, not the one who eventually shows up with good intentions and a higher salary.
People underestimate this because humans are built for linear intuitions: plant seed, water seed, get a tree. But money doesn't grow like a tree. It grows like a rumor, quietly, exponentially, and faster the longer you leave it alone.
The real cost of waiting isn't the missed contribution. It's the lost decades in which money could have been multiplying in the dark.
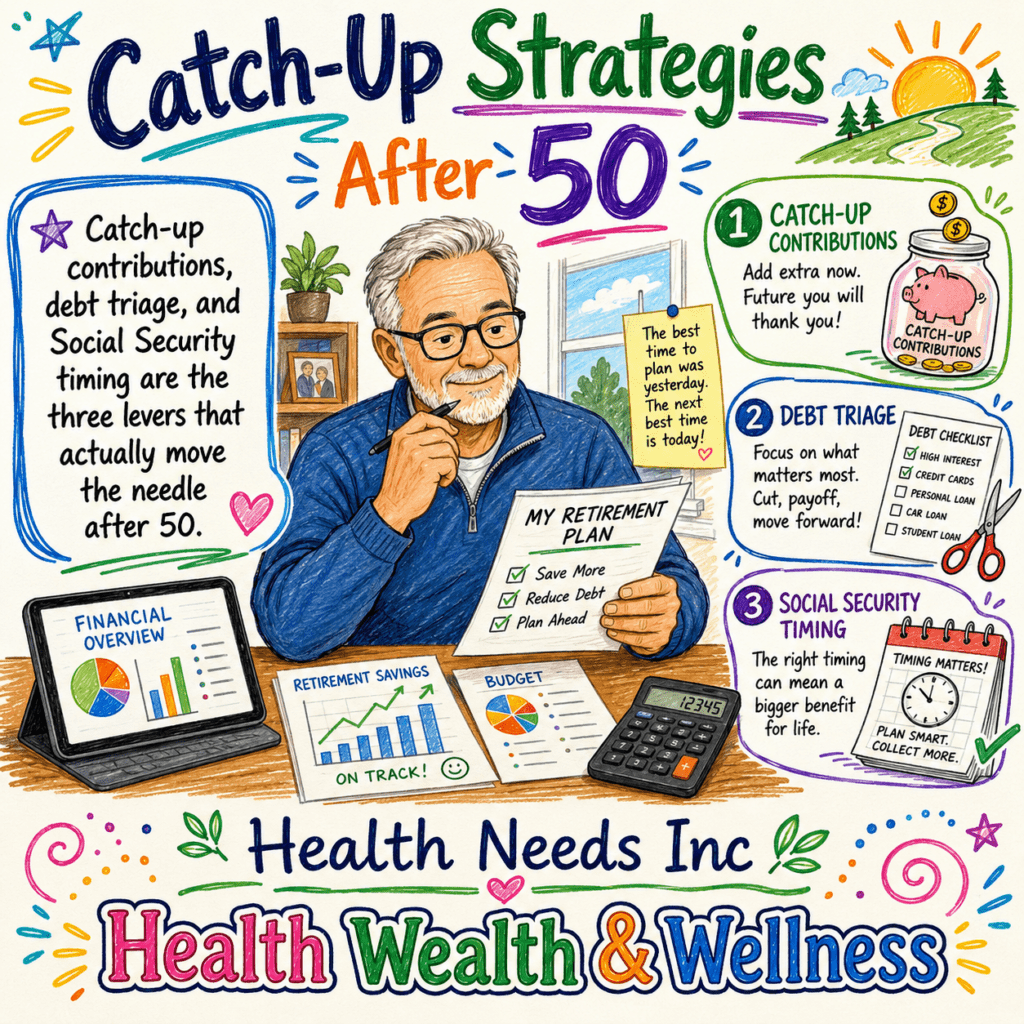
Myth #2: Is It Really Too Late If You're Over 50?

② Ages 60–63 may qualify for an $11,250 catch-up, for a $35,750 total.
③ Delaying Social Security from 62 to 70 can raise the monthly benefit by roughly 77% for someone whose full retirement age is 67; whether delay improves lifetime income depends on longevity and circumstances.
This myth is emotionally seductive because it offers something people secretly crave: permission to surrender.
There is a strange comfort in fatalism. If it is "too late," then one no longer has to endure the moral irritation of responsibility.
But the arithmetic is less melodramatic than the feeling. Your fifties are often your peak earning years.
The children may be leaving. The house may be too large. The lifestyle inflation of middle age can often be cut with surprising speed once you stop pretending every expense is essential.
This is where retirement planning becomes less about elegance and more about aggression. Sell the oversized house no one actually enjoys maintaining.
Cut the car payment that exists mostly as an identity statement. Redirect the money with mechanical consistency.
Catch-up contributions are often discussed as though they were technical footnotes buried in the tax code. In reality, they are an institutional acknowledgment that many lives do not unfold according to the fantasy script.
Divorce happens, illness happens, bad decades happen. The system, in this small way, admits it. The IRS lists the 2026 contribution and catch-up limits.
SELECT A RETIREMENT MYTH TO EXPLORE
Examine the assumptions in your retirement plan
Open each question to see what to check in your own plan. Open it again to close.
Open each question to identify a retirement assumption worth checking.
This counts questions explored, not retirement readiness.Myth #3: Do You Really Need 80% of Your Pre Retirement Income?
Few ideas in personal finance have enjoyed such unearned prestige: "You need 80 percent of your pre-retirement income." Why 80? Because round numbers are emotionally soothing.
This is one of those rules that survives because it sounds authoritative enough to discourage further thought.
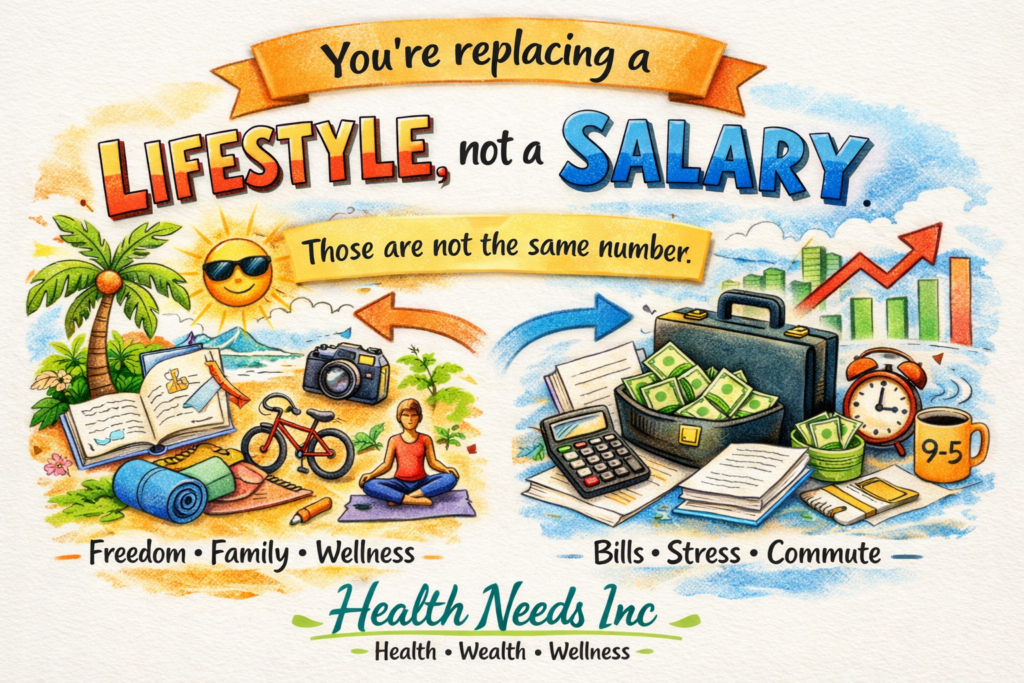
But income is not the thing you are replacing. Lifestyle is.
A person earning $150,000 while saving aggressively, paying payroll taxes, and commuting five days a week may only be actually living on $90,000. Retire that person, and the retirement target drops accordingly.
Another person earning the same salary and spending almost all of it requires something closer to 90%. Same income, entirely different retirement reality.
The broader problem with financial folklore is that it confuses averages with truth. Retirement planning is less about universal percentages and more about the unglamorous anthropology of your own habits. How much do you actually spend?
Not aspirationally. The bank statement knows the truth better than your self-image does. Household spending often falls after retirement on average, but averages conceal large differences in housing, health, family obligations, and discretionary choices.
↪ Deep dive: Why the 80% rule is financial folkloreSimple Cash Flow Calculator
An educational monthly snapshot. It does not include taxes, changing expenses, or market risk.
Myth #4: Is Your 401(k) Really Your Retirement Plan?
 A 401(k) is a tax wrapper, not a plan. Diversify across Roth, HSA, and taxable accounts.
No. It's a box. Saying the 401(k) is your retirement plan is like saying the medicine cabinet is your healthcare strategy. A 401(k) is a container, a tax wrapper, a vessel.
What matters is what sits inside it, what it costs, and whether anyone has actually looked at it in the last five years.
Many people treat workplace retirement accounts with a kind of ceremonial neglect. Money goes in automatically. They never check the fees, they never rebalance, and they couldn't name the funds they own.
This is treated as responsible behavior because contributions happen, when in fact contributions are the beginning of the job, not the end of it.
The quiet villain is fees. A one-percent expense drag sounds trivial. Over thirty years it behaves like a slow leak in a life raft: nothing dramatic, just enough to drown you later.
And the pre-tax concentration risk is a separate problem: a 401(k) heavy retirement portfolio creates a tax timebomb.
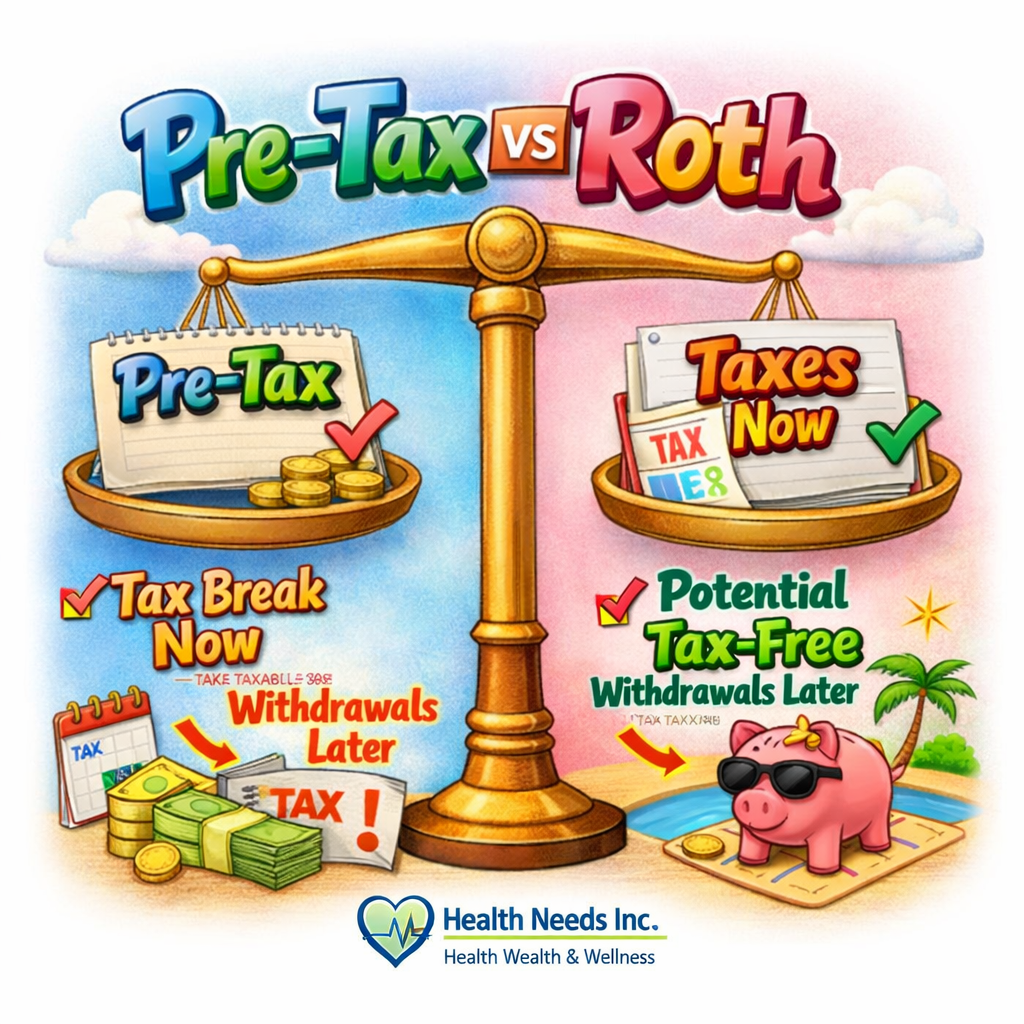
Required minimum distributions generally begin at 73 for people born from 1951 through 1959 and at 75 for people born in 1960 or later. Workplace-plan rules can differ. Tax diversification can provide more control over taxable income, but it does not erase tax risk.
↪ Deep dive: Building a tax-diversified retirement planMyth #5: Can You Really Just Work Longer?
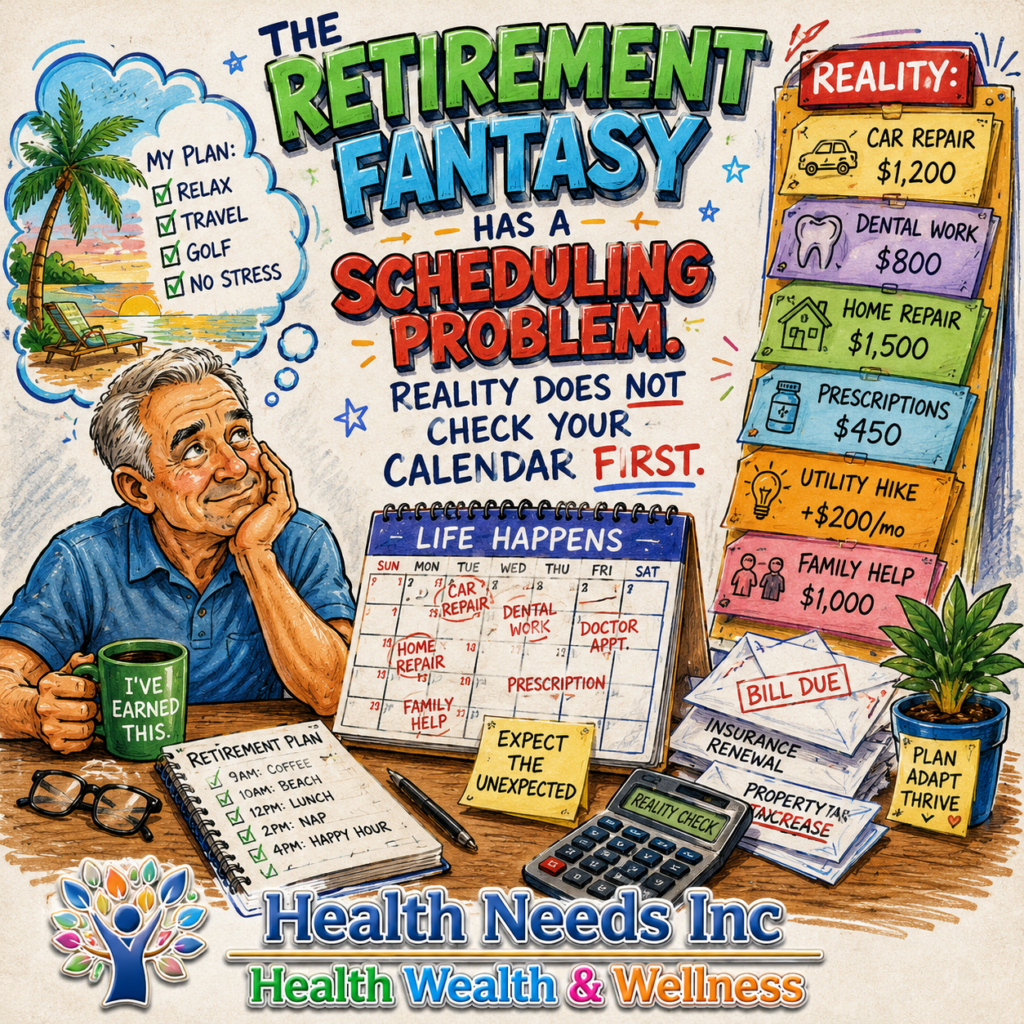
This may be the saddest myth on the list, because it rests on an assumption of bodily loyalty. As though the body has signed some invisible agreement promising to remain useful until the balance sheet improves. It hasn't.
People imagine retirement as a choice. Often it is an event imposed from outside: a diagnosis, a layoff, a spouse who suddenly needs care, an employer who quietly decides that decades of experience have become too expensive.
The modern labor market is not sentimental about aging, and the severance package rarely covers the gap between forced early retirement and Social Security eligibility.
The fantasy of "just one more year" has ruined more retirement plans than market volatility ever did. Hope is not a strategy. It is, at best, a temporary anesthetic. EBRI’s 2026 survey reports that nearly half of retirees retired earlier than planned.
↪ Deep dive: The risk of counting on working longerMyth #6: Do You Really Need a Million Dollars?

Mini Case Study: Same Goal, Different Realities
Person A: $1,000,000 portfolio, renting in a high cost-of-living city. 4% withdrawal = $40,000/year. Rent at $2,500/month = $30,000/year. After rent: $10,000 remains for everything else.
Person B: $600,000 portfolio, owns home outright. 4% withdrawal = $24,000/year, with zero housing payment. Higher discretionary income on $400,000 less saved.
The conclusion: Cash flow and fixed expenses matter far more than a round number. This example is an illustration, not a universal retirement target.
The million-dollar figure became culturally totemic because it sits at a peculiar boundary, large enough to feel like wealth and specific enough to function as a target. It serves less as a planning tool and more as a status symbol masquerading as a threshold.
The actual question is simpler and more personal: what do you spend? First subtract reliable annual income from actual annual spending. Then, as a rough 4% heuristic, multiply the remaining annual gap by 25. The result is a planning estimate, not a personalized target or guarantee. It may be more than a million; it may be substantially less. The round number tells you nothing useful by itself.
↪ Deep dive: How much is enough, the cash flow perspectiveMyth #7: Is the 4% Rule Really a Safe Withdrawal Law?
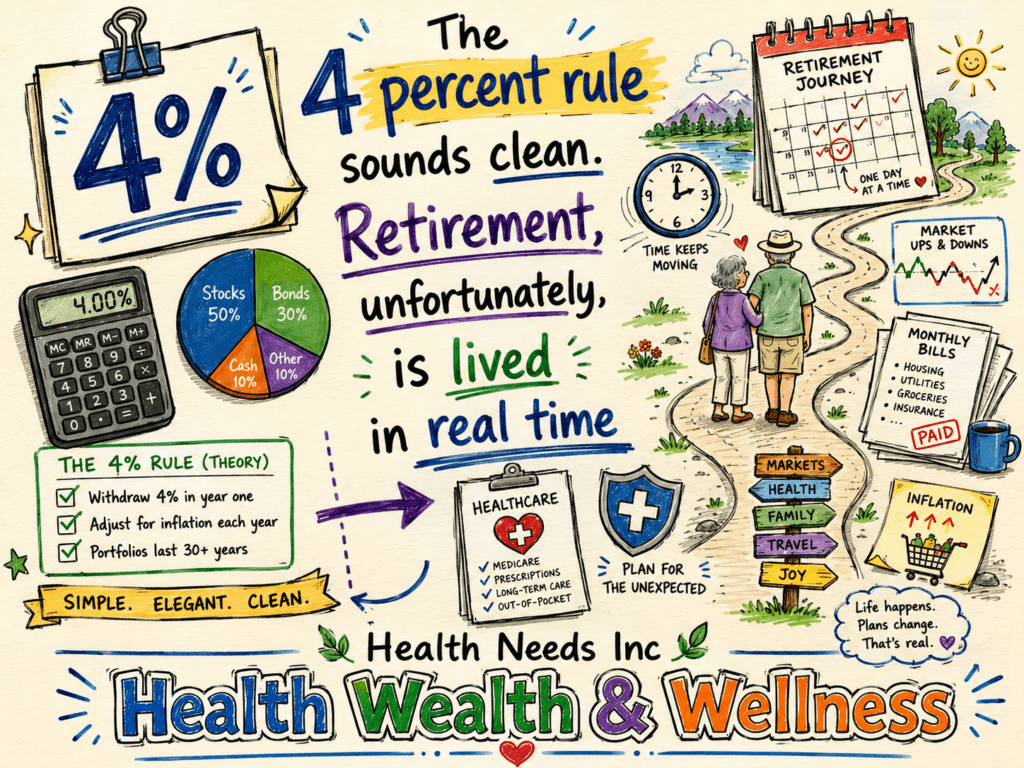
If personal finance has a catechism, this is line one: withdraw four percent per year and your money lasts. The problem is that what began as a cautious academic stress test has been converted by popular culture into a magic number, a law, a religion.
The rule was never meant to be universal. It emerged from historical U.S. market analysis asking what inflation-adjusted starting withdrawal rate could have lasted through difficult 30-year periods under particular portfolio assumptions. Historical survival does not guarantee success in an unknown future—or for a different retirement length, allocation, tax burden, fee level, or spending pattern.
The cruel elegance of sequence risk is this: retire into a bull market and a 4% withdrawal may barely dent your portfolio. Retire into a crash and the same withdrawal can permanently impair your capital before the recovery arrives. Same savings, same average return, entirely different futures. Guardrails and flexible spending can help a plan respond, but they require real willingness to adjust.
↪ Deep dive: The 4% rule, history, limits, and modern updatesRetirement Scenario Projector
Enter a fixed set of assumptions to see one possible portfolio path. This is an educational illustration, not a retirement-readiness decision or probability forecast.
Myth #8: Should You Always Pay Off the Mortgage Before Retiring?

Few financial beliefs carry more emotional force than the paid-off mortgage. People want to die owning the house. And yet emotional satisfaction and mathematical efficiency diverge here in ways worth understanding.
A low-rate fixed mortgage is, in a certain light, a peculiar kind of asset: cheap, long-duration leverage against an appreciating asset, while your freed-up capital compounds in the market. The math often favors investing the extra cash over prepaying. But the math doesn't account for the value of sleeping through the night without imagining catastrophe.
Peace of mind is not irrational. The person who eliminates a mortgage payment and immediately becomes a calmer, more consistent investor may outperform the person who optimizes mathematically but makes worse decisions under stress. Know which person you are, and preserve enough liquid reserves for repairs, healthcare, and ordinary surprises.
↪ Deep dive: Should you pay off your mortgage before retiring?Myth #9: Will Social Security Really Be Enough?
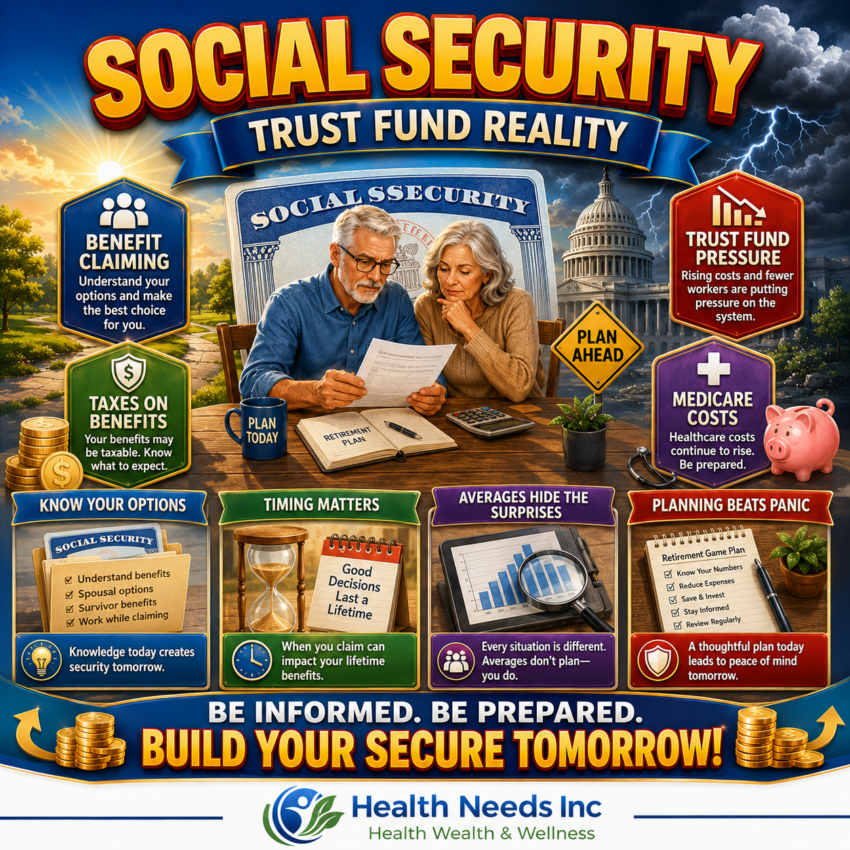 Social Security is an income floor for many households, not a complete retirement plan.
Social Security occupies a strange place in the American imagination. It is simultaneously overestimated as a lifestyle provider and underestimated as a strategic tool. Your own estimate—not a national average—is the useful number. Review it in your Social Security account and build the rest of the plan around the household benefit you can reasonably expect.
The strategic opportunity most people miss is timing. For someone whose full retirement age is 67, waiting until 70 rather than claiming at 62 can raise the monthly benefit by roughly 77%. That is not automatically the best lifetime decision. Health, longevity, cash needs, taxes, opportunity cost, and spousal or survivor benefits all matter. See the SSA's early and delayed retirement factors and the 2026 Trustees summary.
↪ Deep dive: Maximizing Social Security and understanding the trust fundMyth #10: Does Medicare Really Cover Everything?
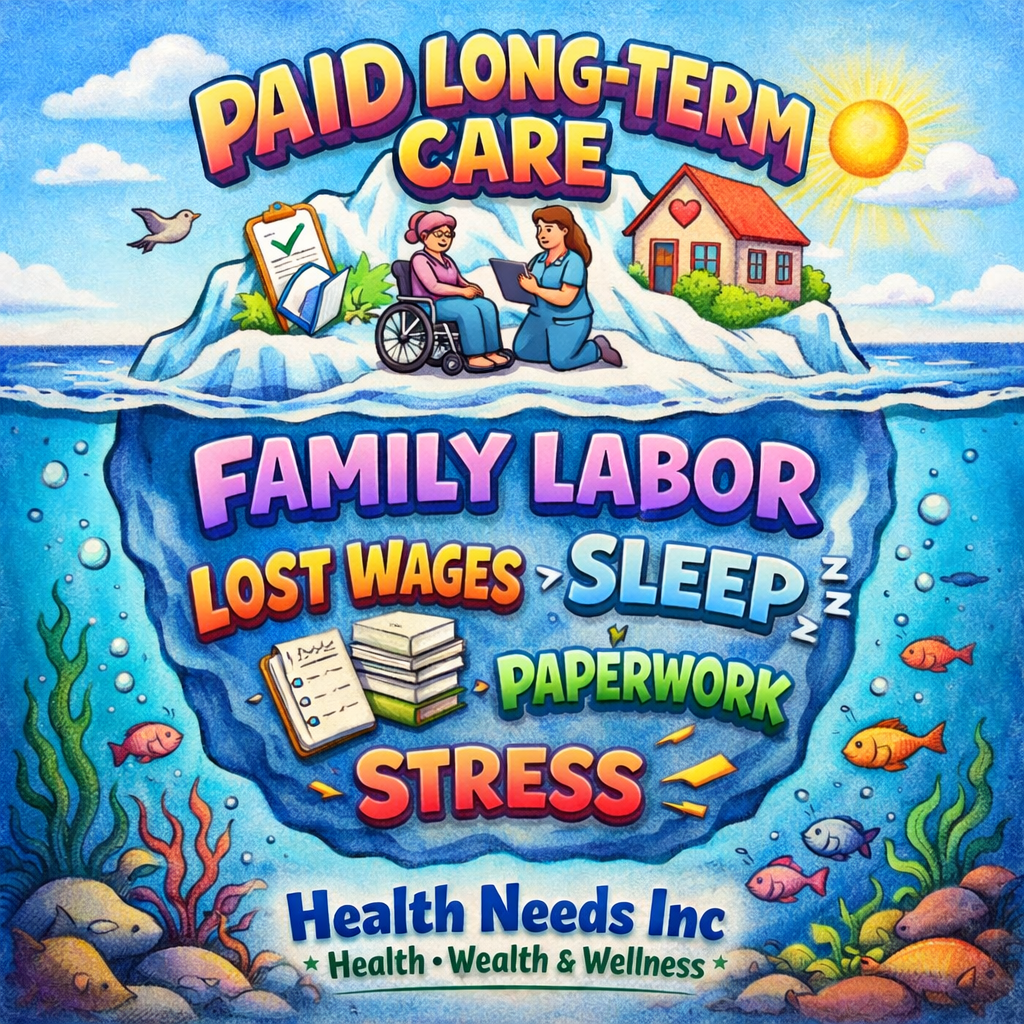 Someone turning 65 has almost a 70% chance of needing some type of long-term services and supports during their remaining lifetime. Medicare does not cover long-term custodial care when that is the only care needed.
This myth deserves special contempt because it is not just expensive; it is catastrophically expensive precisely when people are least able to recover from the financial damage. Medicare covers the emergency. It does not cover the aftermath. And the aftermath is where the money lives.
The important distinction is between eligible short-term skilled care and ongoing custodial care. Medicare generally does not cover long-term assistance with everyday personal tasks when that is the care needed. Funding may involve personal resources, private insurance, or Medicaid for people who meet their state’s eligibility rules; NIA outlines the main payment options.
↪ Deep dive: Long-term care costs and how to plan for themMyth #11: Should You Really Get More Conservative as You Age?
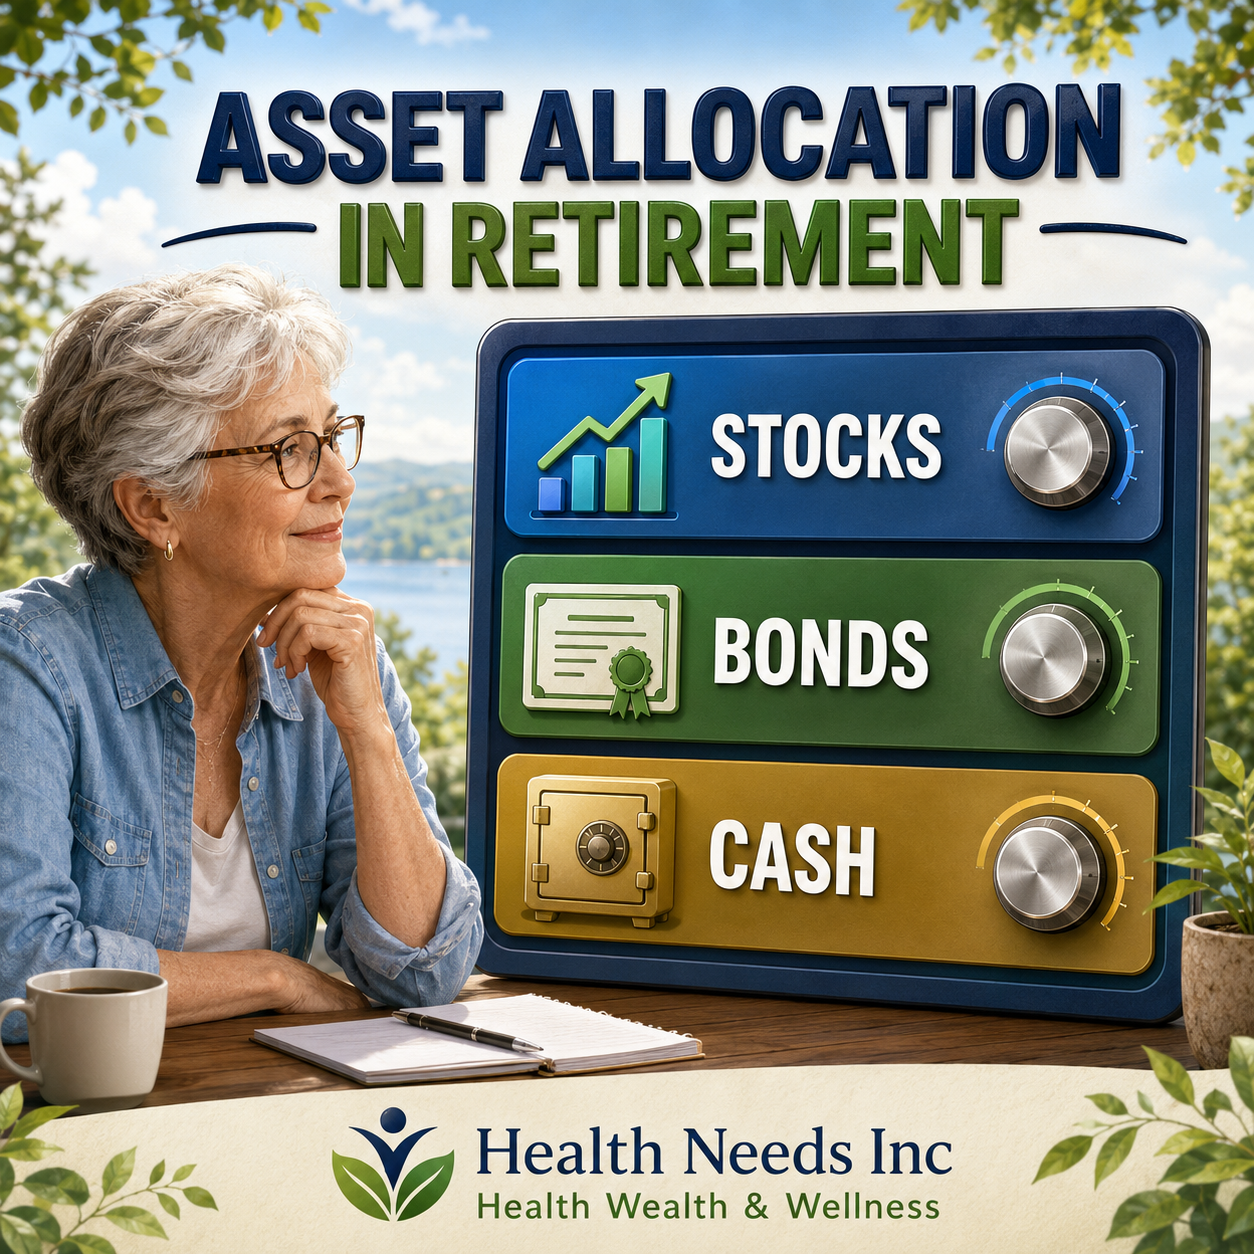
This advice made sense when retirement lasted eight years. It was designed for a different era with different lifespans, lower inflation, and pension income doing most of the heavy lifting. Today, a 65-year-old couple has a meaningful probability that one of them will live past 90. That is a 25-year retirement.
Money sitting in bonds and cash can lose purchasing power when returns fail to keep pace with inflation. The portfolio that avoids stock-market losses but cannot sustain real spending has simply swapped one form of risk for another, quieter one. At the same time, an allocation that causes the owner to panic-sell is not sustainable either. The job is to balance growth, stability, and behavior.
↪ Deep dive: How much equity do retirees actually need?Myth #12: Will Moving to a Cheaper Country Really Solve It?

The fantasy is compelling: a lower-cost country, cheaper housing, and healthcare that appears affordable. For a certain kind of person with the right preparation, it genuinely works. But the people for whom it doesn't work rarely end up in the testimonials.
Healthcare is the first complication. Routine care may be accessible and affordable; a serious diagnosis can change the calculus quickly. Specialist access, insurance exclusions, medical evacuation, and the decision about whether to stay or return home are decisions made under duress with serious money attached.
Visa and tax stability are the second complication. Countries can change residency, taxation, property, and insurance rules. The country that welcomed retirees last decade is under no obligation to preserve the same bargain.
Currency is the third. If your savings are in dollars and your expenses are in another currency, exchange-rate movements can materially change the cost of retirement even when local prices do not move.
And then there is the loneliness, which tends to be the most honestly reported reason people return. Isolation is not free. The people who make international retirement genuinely work have typically spent years building local networks before they officially stopped working. It's not a plan; it's a project.
↪ Deep dive: The real costs of retiring abroadMyth #13: Does Spending Really Decline Automatically as You Age?
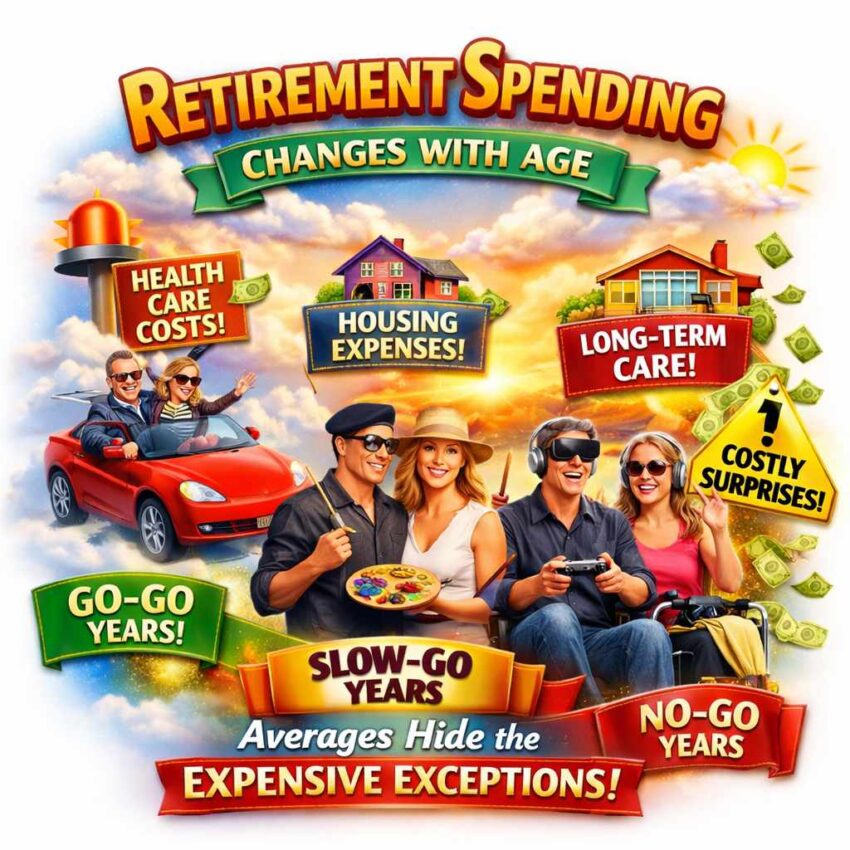
The intuitive model of retirement spending goes like this: you stop working, your income drops, therefore you spend less and it keeps declining until you don't. This is clean, simple, and wrong.
One popular model is the retirement spending smile: more discretionary spending in the early “go-go” years, a quieter middle period, and higher health or care expenses later. It is useful as a prompt, not a prediction. Some households follow it; others spend less almost immediately, maintain a plateau, or face expensive shocks at any age.
The middle phase is the lull. Activity slows, the big trips have been taken, lifestyle equilibrates. This is the period most retirement projections describe accurately. Then comes the final phase: the no-go years. Health costs that Medicare doesn't cover, long-term care expenses, home modifications, prescription drugs, specialist visits, and the personal care that becomes necessary when the body can no longer cooperate with independence.
Late-life costs are routinely underestimated because they are uncomfortable to plan for. A fixed, perfectly smooth spending model can miss both discretionary choices and care shocks. Build a core budget, separate flexible spending, and test irregular expenses instead of trusting the tidiness of a straight line.
↪ Deep dive: The retirement spending smile, planning for three phasesMyth #14: Are Annuities Really Always a Scam?
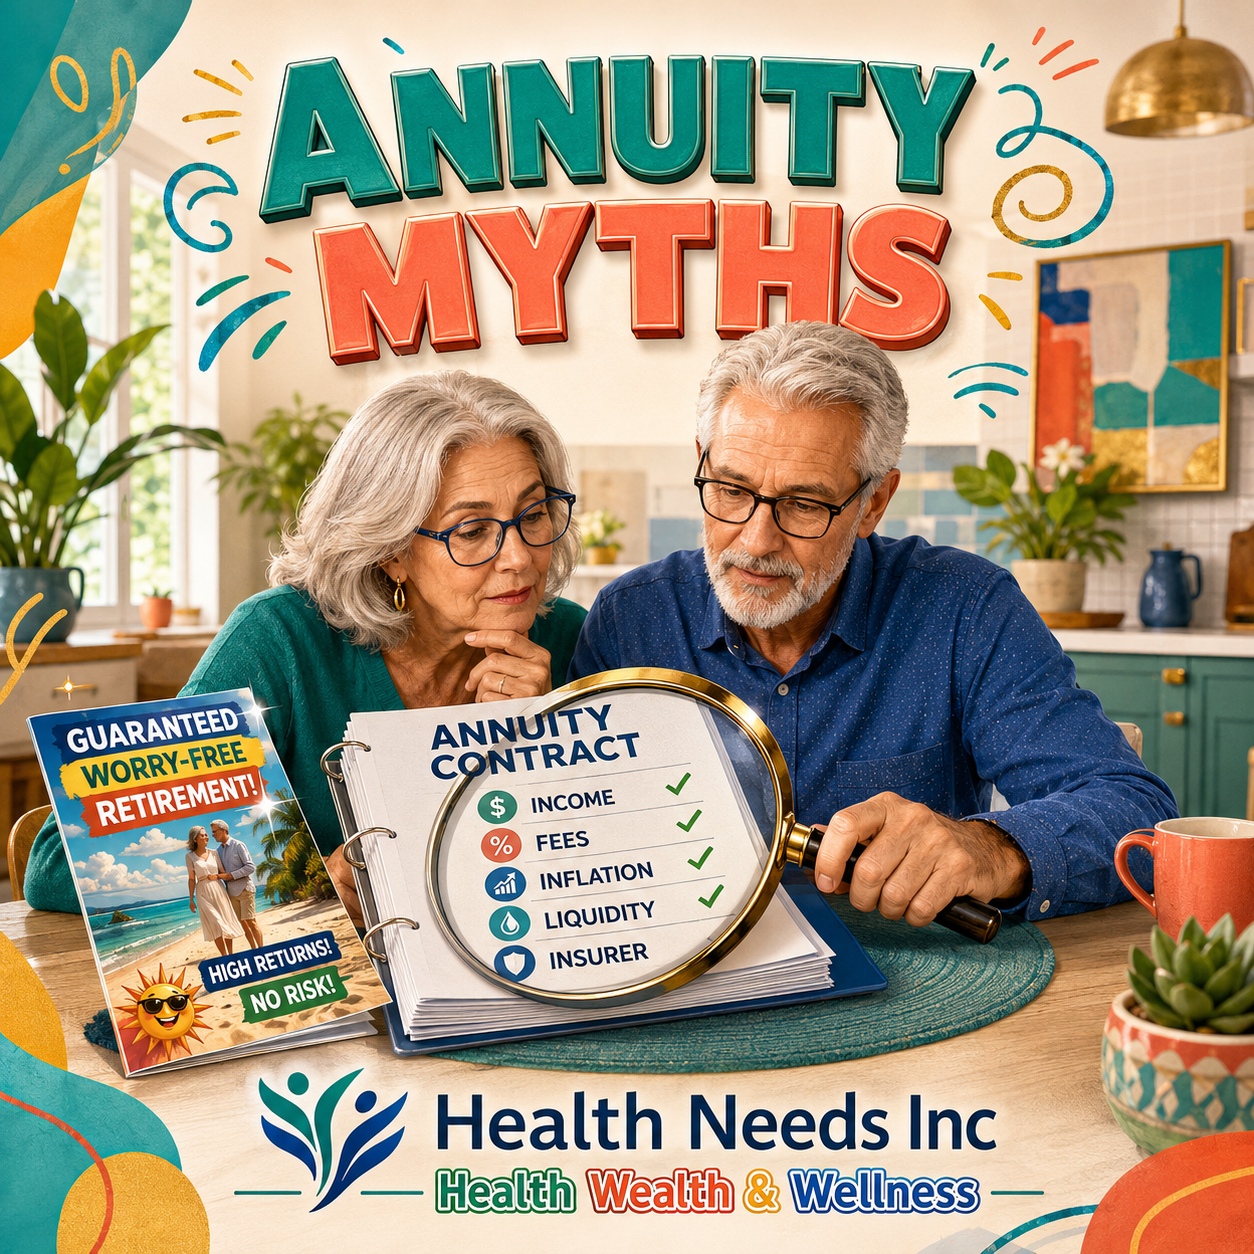
The bad reputation is earned. Variable and indexed annuities sold through commission-based advisors can carry expense ratios that would embarrass an actively managed mutual fund, surrender charges that lock up capital for a decade, and rider combinations so complex that the product brochure requires a law degree to parse. The contempt these products receive is appropriate.
But a single-premium immediate annuity, SPIA, is something else. You hand over a lump sum to an insurer. In return, the contract can provide a monthly payment for life. Payments are subject to contract terms and the insurer's claims-paying ability. Inflation protection, liquidity, death benefits, fees, and applicable state guaranty-association limits all deserve scrutiny.
For someone without an employer pension and with genuine longevity in their family history, a SPIA covering essential expenses is not a scam. It is insurance against the one problem most financial plans quietly fail to solve: the risk of outliving your assets by a decade or more. The objection that you might die early and "lose" the premium confuses insurance with investment. You don't resent your car insurance when you don't crash. The annuity is not a bet on your longevity; it is a hedge against it.
The question is not whether annuities are scams. It is whether a particular instrument, at a particular cost, addresses a real risk in your specific situation. That requires reading the fine print rather than inheriting the reputation.
↪ Deep dive: When (and when not) to consider an annuityMyth #15: Will Your Children Really Take Care of You?
This one doesn't arrive with numbers attached. It arrives with a feeling, a vague comfortable understanding that the family will figure it out. It feels like love, and it functions like a plan until it doesn't.
The problem is that the children who are expected to provide that care are simultaneously trying to pay off debt, save for their own retirement, support their children, and manage demanding careers. Caregiving in the U.S. 2025, research led by AARP and the National Alliance for Caregiving, reports 63 million family caregivers. The burden of caregiving is not a future problem; it is a present one, and it is already substantial.
Expecting adult children to serve as both emotional caregiver and financial guarantor is asking for two full-time jobs from someone who already has one. It tends to produce resentment on both sides: the parent who receives inadequate support and the child who feels permanently indebted to a need they cannot fully meet.
Insurance, earmarked savings, public-benefit planning, housing choices, and a written family care plan are not about distrust. They protect relationships from the strain that money plus obligation plus unspoken expectation reliably produces. The most loving thing you can do for your children's relationship with you in old age is not to require them to become the entire financial safety net.
↪ Deep dive: The family-based retirement plan fallacyDownload the Retirement Survival Kit
Four tools for people who want numbers, not slogans.
- 4% Rule Calculator (Excel & Google Sheets)
- 12-month spending audit worksheet
- Social Security timing decision guide
- Long-term care cost planning checklist
Unsubscribe at any time.
Final Thought: Retirement Is Really About Time, Not Money
Money is only an instrument. Time is the subject. Retirement planning is a disguised conversation about how one wishes to inhabit the final third of life, and what needs to be built now to make that possible.
Every myth on this list ultimately serves the same psychological purpose: to soften the terror of uncertainty. People cling to formulas because formulas offer the illusion that the future can be domesticated. It cannot. But it can be made more survivable.
What planning buys is not certainty. It buys resilience: enough margin to absorb reality when reality inevitably refuses to follow the brochure. Perhaps that is the most honest definition of financial security. Not abundance, not status, not round numbers, but margin, the capacity to absorb life without being shattered by it.
Plan earlier than feels necessary. Save more than feels comfortable. Distrust slogans. Interrogate round numbers. And never confuse cultural clichés for strategy.
↪ Deep dive: How to model uneven retirement expensesQuick Action Summary
- Run a 12-month spending audit. Your bank statement knows your actual lifestyle cost better than any estimate.
- Check catch-up contribution eligibility. For 2026, the general 50+ catch-up is $8,000 for eligible workplace plans; ages 60–63 may qualify for $11,250. The IRA catch-up is $1,100.
- Investigate long-term-care services and costs in your area, then decide which combination of savings, insurance, benefits, housing, and family support belongs in the plan.
- Run the Retirement Scenario Projector below to test a fixed set of assumptions—not to receive a readiness verdict.
Frequently Asked Questions
Medicare may cover qualifying short-term skilled nursing or rehabilitation, subject to its rules. It generally does not cover ongoing help with daily activities when custodial care is the only care needed.
Funding may involve personal resources, private insurance, or Medicaid for people who meet their state's financial and functional eligibility rules. Costs vary substantially by type of care and location, so local planning belongs on every serious retirement checklist.
A dynamic approach means spending less after weak results and allowing more after strong ones rather than following a fixed inflation-adjusted path regardless of conditions. Flexibility can help, but only if the household is willing and able to make those adjustments.
Also weigh time horizon, emergency reserves, risk capacity, and the psychological value of eliminating a required payment. A hybrid approach can balance those goals. The right comparison uses your mortgage, taxes, cash reserves, and actual willingness to accept market losses.
Subtract reliable annual income such as Social Security and pensions. The remaining annual gap is what the portfolio must support. Multiplying that gap by 25 produces a rough 4% planning estimate, not a personalized target or guarantee.
Test taxes, fees, irregular costs, different return sequences, longevity, and spending changes before treating any estimate as a plan.
The 2026 IRA limit is $7,500, plus a $1,100 catch-up for people age 50 or older, for an $8,600 total. Plan terms, compensation, eligibility, and other rules can limit what an individual may contribute; verify current IRS guidance and your plan.
Roth accounts use after-tax dollars; qualified withdrawals can be tax-free, including growth. Holding accounts with different tax treatments can provide flexibility, but the right mix depends on tax law, income, account rules, and individual circumstances.
Treasury Inflation-Protected Securities can provide direct inflation adjustment within fixed income. Social Security's cost-of-living adjustment also helps. A flexible withdrawal policy can respond to inflation and portfolio results, but it requires room to reduce discretionary spending.
Medicare does not cover long-term custodial care when that is the only care needed. Planning may combine personal savings, insurance, Medicaid eligibility planning, housing choices, and family support. Price local options and document preferences before a health event makes every decision reactive.
The mechanism: if the market drops 30% in year two of your retirement and you're withdrawing 4% annually, you're selling shares at depressed prices to fund your living expenses.
Those shares never recover for you personally, even when the market does, because you no longer own them. The same average return earned in a different sequence (good years first, bad years later) produces a completely different outcome.
Managing sequence risk typically involves a cash buffer of one to two years of expenses, a dynamic withdrawal strategy, or a portion of income guaranteed by Social Security or an annuity.
ACA marketplace plans are the other main option and can be subsidized based on income (retirement income from investment withdrawals counts).
For some early retirees, carefully managing taxable income to stay within subsidy thresholds is a meaningful financial strategy. Budget conservatively: healthcare before Medicare is frequently a $12,000–$24,000 per year expense for a couple.
For someone who would otherwise leave money in a default money market fund or make no allocation decisions at all, it is a major improvement. It is not a complete solution for more complex situations: it doesn't account for your other assets, your specific risk tolerance, tax diversification across account types, or whether the fund's particular glide path matches your circumstances.
Check the expense ratio carefully: low-cost index-based target-date funds (under 0.15%) are substantively different from actively managed versions that charge ten times as much.
More Deep Dives
Glossary of Key Terms
- Sequence of Returns Risk
- The danger that poor market returns in the early years of retirement permanently impair a portfolio, even if long-run average returns are fine. Timing matters as much as magnitude.
- Required Minimum Distribution (RMD)
- Mandatory withdrawals from many tax-deferred accounts. They generally begin at 73 for people born from 1951 through 1959 and at 75 for people born in 1960 or later. Account type, employment status, and plan rules can affect timing; missed amounts may be subject to an excise tax.
- Safe Withdrawal Rate (SWR)
- The percentage of a portfolio you can withdraw annually with a low probability of running out over a given time horizon. The 4% rule is the most cited historical SWR.
- Roth IRA
- An individual retirement account funded with after-tax dollars. Qualified withdrawals in retirement are completely tax-free, including growth.
- HSA (Health Savings Account)
- A triple-tax-advantaged account: contributions reduce taxable income, growth is tax-free, and qualified withdrawals are tax-free. After age 65, can be used for any expense (with ordinary income tax, like a traditional IRA).
- Catch-Up Contribution
- Additional retirement contributions allowed for eligible people age 50 or older. For 2026, the general workplace-plan catch-up is $8,000; eligible ages 60–63 may use $11,250. The IRA catch-up is $1,100.
- Fiduciary
- A professional required to act in a client's best interest when serving in a fiduciary capacity. Ask when that duty applies, what services are included, and how the professional is compensated.
- Single-Premium Immediate Annuity (SPIA)
- An insurance contract that converts a lump sum into an income stream that can continue for life under the contract. Guarantees depend on contract terms and the insurer's claims-paying ability; liquidity, inflation protection, death benefits, and state guaranty limits matter.
- Longevity Risk
- The risk of outliving your savings. The core problem retirement planning exists to solve. A 65-year-old couple today has roughly a 50% chance one of them lives past 90.
- Tax Diversification
- Holding retirement assets across accounts with different tax treatments (Roth, tax-deferred, taxable) to manage future tax rates and RMD exposure.
- Inflation Risk
- The erosion of purchasing power over time. At 3% annual inflation, $100,000 in spending power today requires $180,000 in 20 years. A particular threat in long retirements.
- COLA (Cost-of-Living Adjustment)
- The annual increase in Social Security benefits tied to the Consumer Price Index. One of the most valuable features of Social Security and rarely modeled accurately in DIY projections.
- Medigap
- Supplemental insurance that covers costs original Medicare doesn't, such as copayments, deductibles, and coinsurance. Sold by private insurers, regulated by federal standards.
- Long-Term Care Insurance
- Insurance designed to help cover qualifying long-term services and supports at home or in a facility. Pricing, underwriting, benefits, exclusions, inflation options, and premium-change risk vary by policy and purchase age.
- Target-Date Fund
- A mutual fund that automatically adjusts asset allocation as you approach a designated retirement year. Useful starting point; verify the fees and glide path before relying on it exclusively.